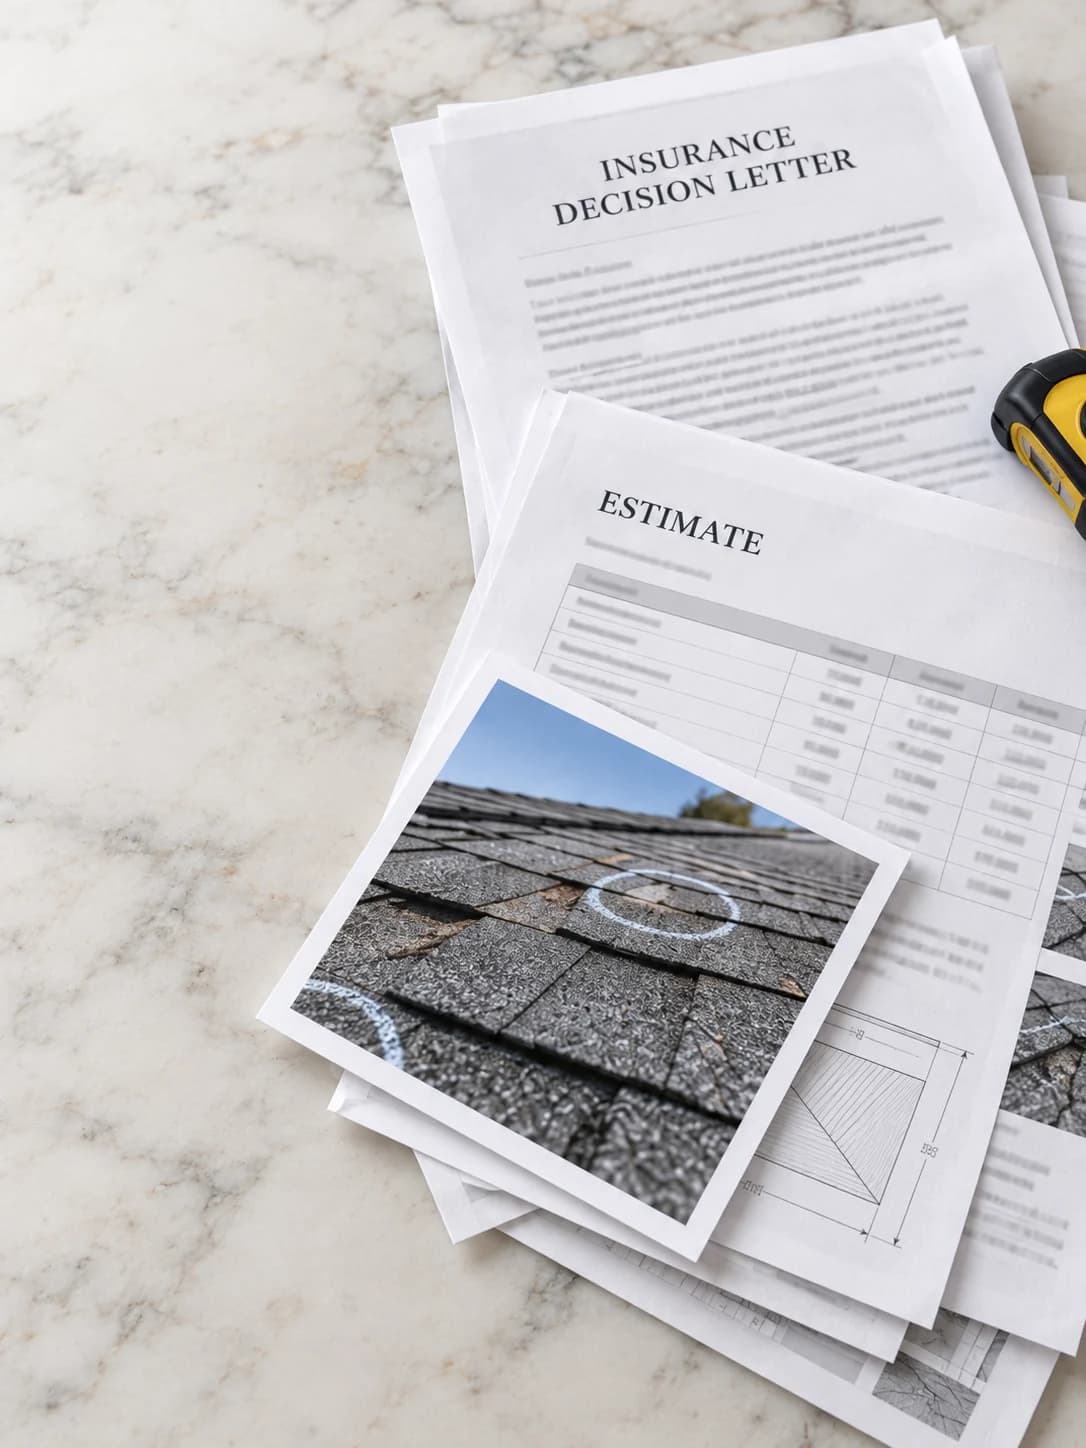
APPRAISAL
Is appraisal appropriate?The details matter.
Appraisal can resolve certain amount-of-loss disputes when the policy authorizes it. It is not the right path for every claim.
UNDERSTAND YOUR OPTIONS
Begin with the whole claim record.
Before coordinating appraisal, we evaluate policy language, dispute type, documentation readiness, economics, and deadlines. Appraisal does not decide every coverage question, and it is never automatic.
WHAT WE LOOK AT
The details that guide the next step.
- 01
Confirm whether the policy includes an appraisal provision
- 02
Determine whether the dispute is appropriate for appraisal
- 03
Assess whether the evidence package is ready
- 04
Consider economics, timing, and open documentation gaps
- 05
Coordinate appraisal readiness when appropriate
- 06
Keep the homeowner informed about process and next milestones
KEEP EXPECTATIONS CLEAR
What a review can and cannot tell you.
- Not every denied or underpaid claim should go to appraisal
- Appraisal does not guarantee a higher award
- Appraisal is not a substitute for legal advice on coverage disputes
- Invoking appraisal without understanding the policy can create risk
This page is educational and does not create a public-adjuster relationship. Representation begins only after a written agreement. No outcome is guaranteed.
Explore another claim situation.
READY FOR A CLEARER NEXT STEP?
Let’s take a look at your claim.
Send the documents you have. We will review the file and let you know whether it appears appropriate for engagement.
Get a Free Claim Review